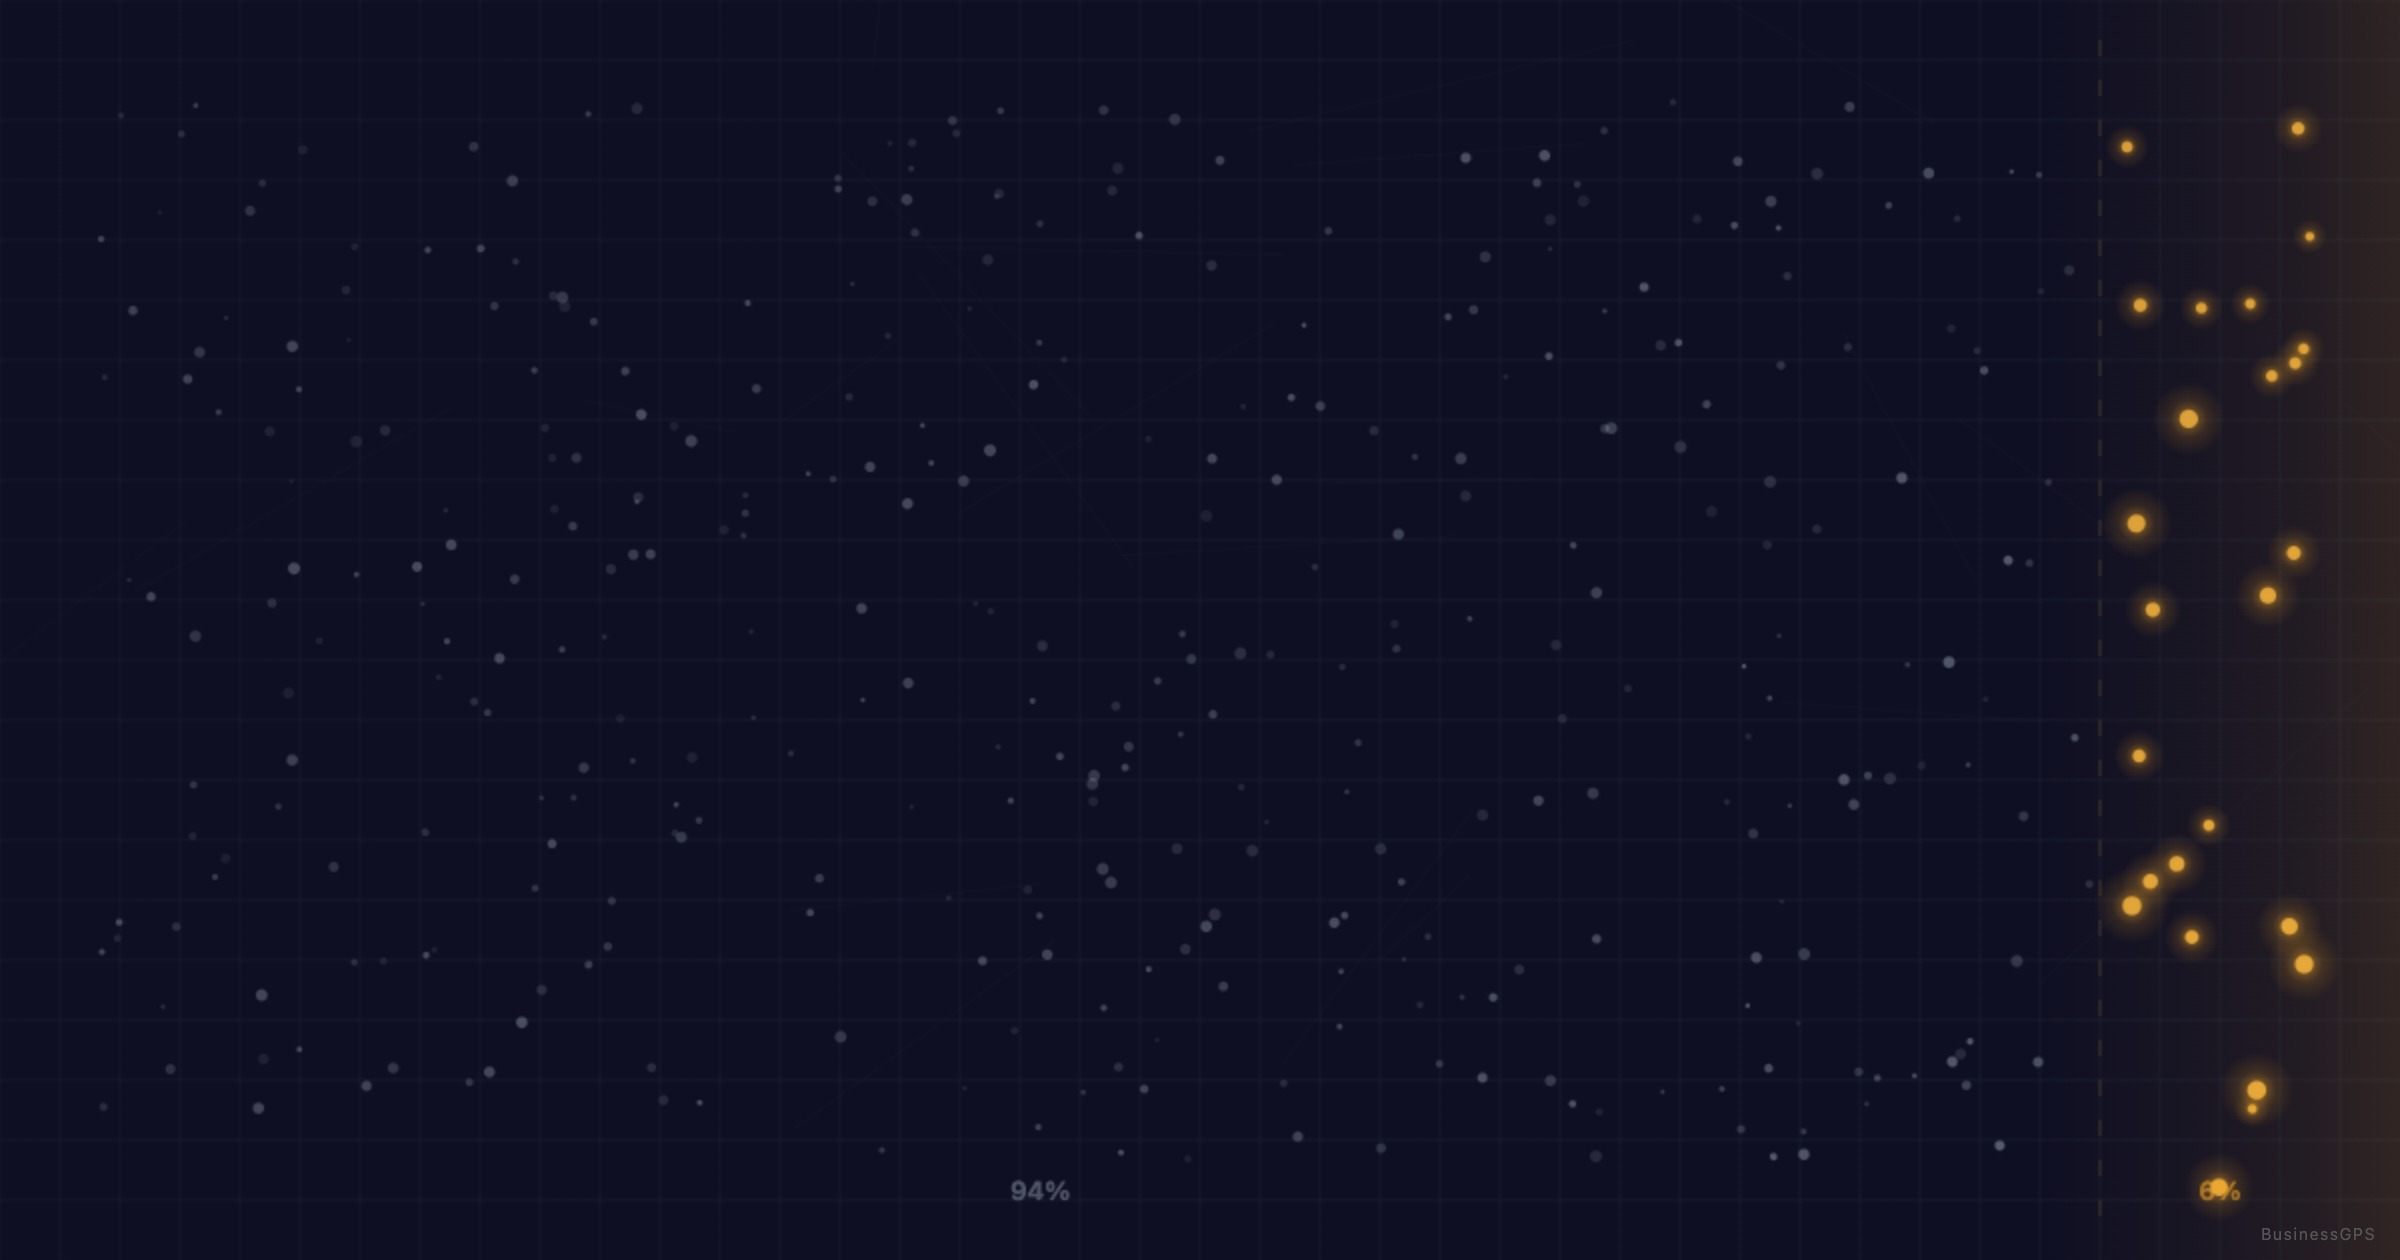
88% of enterprises have adopted AI. Six percent are capturing meaningful value from it.[^5] That gap is not a technology problem. It is a transformation capability problem, and it is freezing the middle of the enterprise landscape solid.
We call it the Frozen Middle. Roughly 17,000 enterprises across the US and UK mid-market sit between two positions: they have adopted AI (the easy part), and they have not built the organisational capability to make it productive (the hard part). They are not failing. They are not succeeding. They are stuck.
This article is about why they are stuck, what is structurally different about the organisations that are not, and what the frozen middle can do about it — starting this quarter.
The 88/6 Gap Is Not About Tools
The instinct, when confronted with an adoption-to-value gap this large, is to blame implementation. Bad tooling. Wrong vendors. Insufficient training. But the data does not support that reading.
The National Bureau of Economic Research published a study in early 2026 — Bloom et al., surveying 6,000 executives — that found 80-90% of firms using AI report zero measurable productivity impact.[^6] Not negative impact. Zero. These firms bought the tools, deployed the platforms, ran the pilots. Nothing moved.
PwC's 2026 Global CEO Survey tells the same story from the top. Of 4,454 CEOs surveyed, 56% report zero financial payoff from AI investments.[^11] Not "disappointing returns." Zero payoff.
Deloitte's State of Generative AI report, also 2026, surveyed 3,235 business leaders. Only 20% described their organisation as "highly prepared" for AI-driven transformation.[^12] Two-thirds said AI is advancing faster than their organisation can absorb it.
Read that again. Two-thirds.
These are not companies that skipped the AI wave. They surfed it. They are drowning anyway.
What the 6% Actually Did
McKinsey's 2025 data identifies a thin layer of organisations — roughly 6% — that have crossed from adoption to high performance.[^5] BCG's research calls them "future-built" companies and puts a number on the difference: 1.7x revenue growth and 3.6x total shareholder return compared to peers.[^17]
What separates them is not superior technology selection. It is not bigger budgets.
Look at what they did differently. They treated transformation capability as an asset class — something to be built, maintained, and depreciated on a schedule, the same way you would treat physical infrastructure. They invested in internal architecture: the people, processes, and governance structures that allow an organisation to absorb a new capability, embed it in operations, and then do it again when the next one arrives.
BCG's own analysis is blunt: "capabilities atrophy if not tested and maintained."[^2] The future-built 6% understood this. They did not just acquire tools. They built — and kept building — the organisational muscle to absorb, adapt, and redeploy those tools as conditions changed. When the model improved, they could reconfigure. When the use case shifted, they could pivot. When the vendor landscape moved, they were not locked in.
The remaining 94% bought tools and hoped the capability would follow. It did not.
This distinction matters enormously for anyone holding a transformation budget. McKinsey's capability-building research found that organisations investing in capability development were 4.1x more likely to succeed at transformation and generated 2.2x the EBITDA improvement.[^1] Four times. Not a marginal edge — a structural multiplier. The mechanism is not mysterious. The question is why so few organisations do it.
The Capability Transfer That Never Happens
Here is where the structural problem lives.
The global AI consulting market is projected to grow from $14 billion to $116 billion by 2035.[^7] That is not a typo. Enterprises are spending unprecedented sums on external expertise to navigate AI transformation. And yet — McKinsey's own 2026 data shows 62% of enterprises are still "experimenting" with AI, with fewer than 10% operating at full scale.[^14]
Money is flowing. Capability is not transferring.
If you have sat through a transformation steering committee where the RAG status is green and everyone in the room knows it is not — you have seen this dynamic in person. The consultants are delivering. The dashboards look healthy. But when the engagement ends, the organisation's ability to sustain, adapt, and extend the work ends with it. Accenture found that fewer than 15% of enterprises even track EBIT or revenue impact from their AI investments.[^4] The measurement infrastructure does not exist, let alone the capability.
Gartner projects that 40% of agentic AI projects will be cancelled or scaled back by 2027.[^13] That is not a prediction about AI technology failing. It is a prediction about organisations failing to build the internal architecture required to operate it.
A recent industry survey found 87% of enterprises say consultancies are not easing transformation fatigue.[^16] Think about what that number means for a moment. The firms you hire specifically to help you through transformation are, in the overwhelming majority of cases, not reducing the burden. They may be delivering excellent work. The burden remains.
The dependency dynamic is self-reinforcing. The more external capability you buy, the less internal capability you develop. The less internal capability you develop, the more external capability you need next time. Each engagement makes the next one more necessary, not less. The consulting firms know this. Many have built their business models around it — recurring revenue from recurring dependency. We do not say that as criticism. It is a rational commercial strategy. But if you are on the buying side, you should understand the dynamic you are funding.
This is not a failure of intent on either side. It is a structural gap. Consultancies are hired to deliver outcomes. They are rarely hired — and even more rarely scoped — to transfer the capability to deliver those outcomes independently. The transfer mechanism does not exist in most engagement models. So the capability walks out of the building when the team does.
And the handover that follows often makes things worse, not better. Many enterprises transition from delivery consultants to application management or business process outsourcing providers — a support layer that knows how to run the new system but rarely how to change it. The knowledge transfer from project team to support team is notoriously thin. The result is an organisation that can operate what was built but cannot adapt it. When business requirements shift — and they always shift — the enterprise is back to buying external help, this time from a support provider who may understand the system even less deeply than the original delivery team.
This is not an argument for doing everything in-house. Outsourcing support and operations is often the right strategic choice. The problem is making that choice without understanding what capability you are retaining, what you are delegating, and what you are losing. The frozen middle is not full of organisations that made bad outsourcing decisions. It is full of organisations that made unconscious ones — defaulting to external dependency without ever mapping what they could do themselves if they chose to.
The Absorption Problem Has a 250-Year Pattern
This is not new. It looks new because the technology is new. The organisational failure mode is ancient.
Every major industrial transition in the past 250 years has produced the same pattern:[^20] a new capability arrives, enterprises adopt it, and then a gap opens between adoption and productive use. That gap gets closed — eventually — by the emergence of a new management discipline designed specifically for that absorption challenge.
Steam power produced mechanical engineering as a management discipline. Electrical power produced industrial engineering. Mass production produced operations management. Information technology produced IT governance frameworks like COBIT and ITIL. Each time, the discipline lagged the technology by years or decades. Each time, the enterprises that developed the discipline earliest captured disproportionate value.
David Teece's dynamic capabilities framework — first articulated in 1997, refined in 2007 — describes exactly this mechanism.[^8] Competitive advantage belongs to organisations with the capacity to sense, seize, and reconfigure resources — regardless of which resources they started with. The capability to change is itself a capability.
Geoffrey Moore's core/context distinction sharpens this further.[^19] Every organisation must continuously reclassify what is core (differentiating) and what is context (necessary but non-differentiating). AI is accelerating this reclassification at a pace that most management frameworks were not designed to handle. What was core last quarter may be context now. What was impossible six months ago may be table stakes today.
The meta-capability — the ability to continuously perform that reclassification — is becoming the defining competence of the AI era. Not the ability to use AI. The ability to keep reorganising around it as it changes. That is a fundamentally different capability, and almost no one is building it deliberately.
Why Maturity Models Are Not Enough
The standard response to a capability gap is a maturity model. CMMI, Prosci, the usual suspects.[^18] Assess where you are, define where you want to be, plot the journey.
These frameworks are useful for stable-state capability development. They are insufficient for what is happening now.
The rate of technological change means that by the time an organisation completes a maturity assessment, the target state has shifted. The Department of Defense recognised this problem years ago in its JCIDS framework — building temporal capability planning into acquisition precisely because static gap analysis fails in dynamic environments.[^21]
BizBOK's capability mapping provides what the IIBA calls a "Rosetta Stone" between strategy and execution — a shared language for identifying what capabilities exist, where they sit, and what gaps remain.[^9] TOGAF's Phase B includes explicit capability gap analysis.[^10] These are powerful diagnostic tools. But diagnostics without a transfer mechanism produce reports, not capability.
The frozen middle is full of excellent assessments. Filing cabinets — digital and literal — packed with gap analyses, maturity scores, and transformation roadmaps. What it lacks is the architecture to act on them. The diagnosis is rarely wrong. The transfer mechanism is almost always absent.
The £116 Billion Question
Token pricing for large language models has fallen by a factor of 1,200 — from roughly $600 per million tokens to $0.50.[^15] The technology is no longer the bottleneck. Access is no longer the bottleneck. Cost is no longer the bottleneck.
The bottleneck is the organisational capability to absorb, operationalise, and govern what is now cheaply and abundantly available. That bottleneck will not be cleared by buying more technology. It will not be cleared by hiring more consultants, though both may play a role. It will be cleared by building — inside the enterprise — the transformation capability that currently walks out the door at the end of every engagement.
This is what Transformation Capability Management addresses: the systematic architecture for building, transferring, and sustaining transformation capability within the enterprise itself. Not as a one-off initiative. As an ongoing organisational discipline — the same way financial management, IT governance, and operations management became permanent functions when their respective absorption crises demanded it.
The 6% figured this out early. The question for the remaining 17,000 is whether they will figure it out in time — or whether the frozen middle becomes permanent.
Your Waypoint
Pull your last three transformation programme close-out reports. For each one, answer two questions:
First: What capabilities were the programme supposed to build inside your organisation — not deliver as outputs, but build as repeatable internal capacity?
Second: Six months after the programme ended, which of those capabilities can your teams still execute without external support?
If the gap between those two answers is wide, you are looking at a capability transfer failure. The programme may have succeeded on every deliverable and still left your organisation no more capable than before it started.
Now ask a third question: for each gap, was that a deliberate choice or an accident? Some capabilities are better outsourced — that is a legitimate strategic decision. But if you cannot point to the meeting where someone decided "we will rely on a third party for this capability, and here is how we will govern that dependency" — then the gap is not strategy. It is drift.
Map that gap. Separate the deliberate from the accidental. The deliberate outsourcing decisions are fine — govern them well. The accidental ones are where your next transformation investment will either compound or evaporate.
For a deeper look at the structural dynamics behind the capability transfer problem, the TCM Crisis Report lays out the full evidence base, including the 45-step methodology for closing the gap systematically.
References
[^1]: McKinsey & Company, "To Make a Transformation Succeed, Invest in Capability Building." 4.1x success rate, 2.2x EBITDA benefits. [^2]: BCG, "Building Capabilities for Transformation That Lasts" (2016). "Capabilities atrophy if not tested and maintained." [^4]: Accenture State of AI Adoption Survey (2025-2026). <15% track EBIT/revenue impact. RSM (2025): 76% have GenAI budgets; 47% goes to AI consulting. [^5]: McKinsey Global Survey on AI, 2025. 88% adoption, 6% high performers. [^6]: Bloom, Davis, Barrero, Meyer et al. (2026). "Firm Data on AI." NBER Working Paper w34836. 80-90% zero impact, 6,000 executives. [^7]: AI consulting market: $14.07B in 2026, projected $116B by 2035 (26.5% CAGR). [^8]: Teece, D.J., Pisano, G., & Shuen, A. (1997). "Dynamic Capabilities and Strategic Management." Updated Teece (2007). [^9]: BizBOK Guide v14 (March 2025). Capability map as "Rosetta Stone of Business/IT Alignment." [^10]: TOGAF Standard v9.2. Chapter 28: Capability-Based Planning. Phase B gap analysis. [^11]: PwC Global CEO Survey (2025-2026). 4,454 CEOs, 56% zero AI payoff. [^12]: Deloitte AI Readiness Survey (2026). 3,235 leaders, 20% highly prepared. [^13]: Gartner (2026). 40%+ agentic AI projects cancelled by 2027. [^14]: McKinsey (2026). 62% experimenting, <10% full-scale deployment. [^15]: Token pricing: $600/M tokens (2020) to $0.50/M tokens (2026). 1,200x reduction. [^16]: Management consulting industry research (2026). 87% say consultancies NOT easing transformation fatigue. [^17]: BCG (2025). "How CEOs Are Scaling AI." Future-built companies: 1.7x revenue, 3.6x TSR. [^18]: CMMI (Carnegie Mellon/ISACA) and Prosci Change Management Maturity Model. [^19]: Moore, G.A. (2005). Dealing with Darwin. Core/context distinction. [^20]: Pattern analysis across 250 years of technology transitions. [^21]: US DoD JCIDS. RAND Corporation capability planning frameworks.